
Saving a deposit is the single biggest barrier between renters and their first home — so a scheme that cuts the deposit to just 2.5% deserves a close look. The government’s new Your First Home scheme, announced on 26 September and set to be confirmed at the Autumn Budget on Wednesday 28 October, revives the Help to Buy idea for a new generation: a small deposit, a 20% government equity loan, and a much smaller mortgage. Here is everything known so far, the worked numbers, and the catches to watch for.
Your First Home at a Glance
| Your deposit | 2.5% of the purchase price |
| Government equity loan | Up to 20% of the property’s value, interest-free for the first five years |
| Your mortgage | The remaining 77.5% |
| Where | England only |
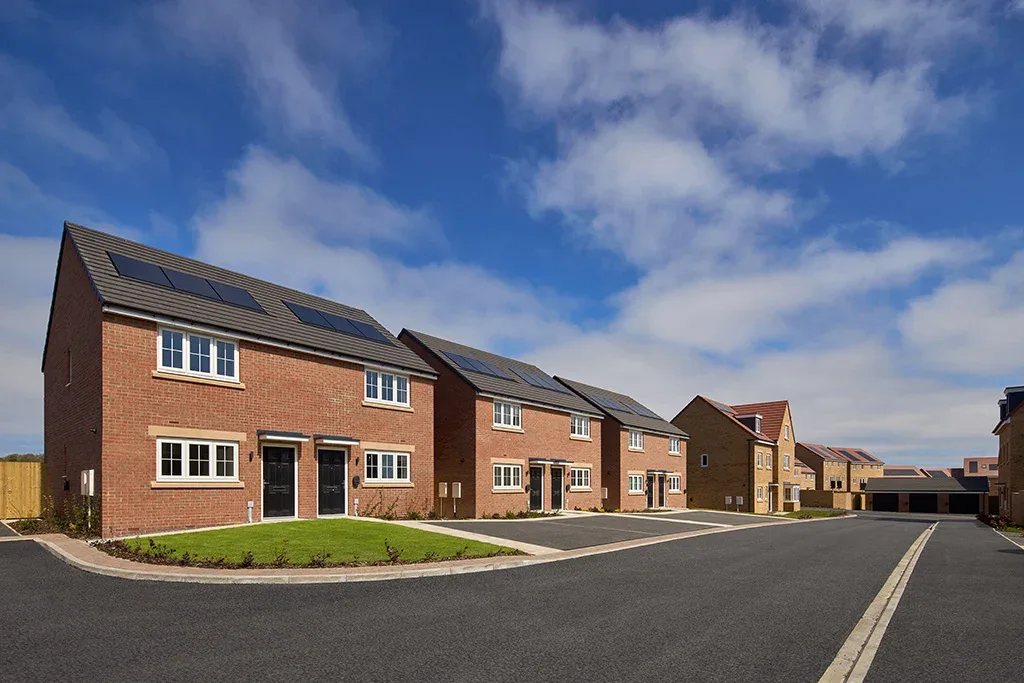
| What you can buy | New-build homes from developers signed up to the scheme |
| Maximum property value | £600,000, with local price caps to be set |
| Who it is for | First-time buyers — a household income cap will apply (figure to be confirmed) |
| When | Full rules at the Budget on 28 October; pre-registration expected to open by the end of 2026 |
How the Money Works: A £300,000 Example
On a £300,000 new-build home, the scheme splits the price three ways. Your deposit is £7,500 (2.5%). The government’s equity loan covers £60,000 (20%). That leaves a mortgage of £232,500 — instead of £285,000 on a standard 95% mortgage, which would also have needed a £15,000 deposit.
Because you are borrowing less, the monthly bill falls too. At an illustrative 5.5% over 25 years, the £232,500 mortgage costs about £1,428 a month, against roughly £1,750 for the £285,000 loan — a saving of around £322 a month, matching the government’s claim that buyers could save “hundreds of pounds per month” compared with a 95% mortgage. The smaller loan also means most buyers will qualify for a 75% loan-to-value mortgage rate rather than a pricier 95% one.

Repaying the Government’s 20%
The equity loan is not a gift — it is a share of your home. According to the government’s announcement, the loan is interest-free for the first five years (the interest charged after that is one of the details the Chancellor will confirm at the Budget) and must be repaid in full when you sell, within 25 years, or when your main mortgage ends.
The crucial detail: you repay 20% of whatever the home is worth at the time, not the amount you borrowed. If your £300,000 home rises to £350,000, you repay £70,000. If it falls to £270,000, you repay £54,000. You share both the gains and the pain with the government.
Who Can Apply — and What Is Still Unknown
The scheme is aimed squarely at first-time buyers in England who have a regular income but cannot save a large deposit or call on the “Bank of Mum and Dad”, in the Prime Minister’s words. To target that help, there will be a household income cap and local property price caps — but the actual figures will only be published at the Budget. You will also only be able to buy from developers who sign up to the scheme (developers are expected to contribute towards its costs), and applicants with substantial savings are expected to be excluded.
Until 28 October, then, buyers, developers and mortgage advisers are all working from an announcement, not the scheme rules. That gap matters for anyone tempted to reserve a plot on the strength of a headline.

The Catches Worth Knowing
New-build only. The scheme cannot be used on existing homes. Industry voices, including Yorkshire Building Society, argue it should be extended to second-hand properties — both to help more buyers and to stop chains jamming up. New-builds also often carry a price premium over similar existing homes, which can quietly eat part of the benefit.
Demand could push prices up. Help to Buy, which ran from 2013 and helped more than a third of a million buyers, was criticised for inflating new-build prices. Experts are already warning against an artificial new-build bubble if Your First Home launches without enough supply behind it.
The loan is a share, not a fixed debt. If house prices climb, the amount you owe the government climbs with them — as the worked example above shows.
What First-Time Buyers Can Do Now
You cannot apply yet, but you can be ready. Even at 2.5%, a deposit on a £300,000 home is £7,500, plus moving costs — our free Deposit Savings Planner shows how long that takes to save at different monthly amounts. Next, test the mortgage itself: run the 77.5% loan through the Affordability Calculator so the monthly figure is no surprise. The full set of tools sits on the UK Home Buyer Toolkit page, and when pre-registration opens — expected by the end of 2026 — having your deposit, credit file and paperwork in order will put you at the front of the queue.
Frequently Asked Questions
Is the Your First Home scheme replacing Help to Buy?
It is effectively its successor. Help to Buy closed to new applicants in England in 2022; Your First Home revives the same model — an equity loan on new-builds — with a smaller minimum deposit of 2.5% instead of 5%.
When can I apply for Your First Home?
The full rules, costs and timetable will be set out at the Autumn Budget on 28 October 2026. Pre-registration for buyers is expected to open by the end of 2026.
Can I use Your First Home on any property?
No. It covers new-build homes in England only, bought from developers participating in the scheme, up to a maximum value of £600,000 with local price caps also applying.
What happens if my home falls in value?
The equity loan is a percentage share. If your home is worth less when you repay, you repay 20% of the lower value — the government shares the loss as well as the gain.
The Bottom Line
Your First Home could genuinely change the maths for first-time buyers: half the deposit of a 95% mortgage, a smaller loan, and hundreds of pounds a month saved. But the two numbers that decide who it actually helps — the income cap and the local price caps — do not exist in public yet. The sensible move is to prepare now and judge the scheme on the detail published on 28 October, not the headline.
Comments are closed.